Hair transplant insurance coverage explained: 2026 UK guide

Hair transplant insurance coverage is excluded under virtually all UK private medical insurance policies because the procedure is classified as elective cosmetic surgery rather than medically necessary treatment. This applies whether you hold a standard PMI policy, a comprehensive health plan, or rely on NHS provision. Hair loss affects roughly 6.5 million men in the UK alone, yet the pathway to surgical restoration remains entirely self-funded for the vast majority. Understanding why coverage is denied, what rare exceptions exist, and how to plan financially is the most practical starting point for anyone considering a procedure.

Why do most insurance policies exclude hair transplant coverage?

Private medical insurance policies in the UK universally exclude cosmetic surgery and elective treatments, and hair transplants fall squarely within that category. The underlying logic is straightforward: PMI is designed to fund acute, treatable medical conditions that arise unexpectedly, not procedures chosen to improve appearance. Hair loss, even when distressing, does not meet the clinical threshold for medical necessity under standard underwriting criteria.

The exclusions written into most PMI policies cover a predictable set of categories:

  • Cosmetic and aesthetic surgery of any kind
  • Pre-existing conditions present before the policy start date
  • Chronic conditions without a defined acute episode
  • Elective procedures not deemed clinically urgent
  • Treatments for hair loss, including Follicular Unit Extraction (FUE) and Follicular Unit Transplantation (FUT)

Moratorium underwriting automatically excludes any condition that existed within five years prior to the policy start date, without requiring full disclosure from the patient. This means that if you experienced hair thinning before taking out a policy, any related treatment claim will be denied automatically. The insurer does not need to investigate further.

Pro Tip: Ask your insurer for a written list of specific exclusions before you purchase any policy. Verbal assurances from sales staff carry no legal weight at the point of claim.

Aviva’s Healthier Solutions plan is a useful reference point. Cosmetic surgeries remain excluded under that policy while acute conditions, diagnostic tests, and outpatient treatments are covered. This pattern is consistent across the market. No standard UK PMI product covers hair transplantation.

What are the rare exceptions where NHS or insurance might cover a hair transplant?

The NHS does not fund hair transplants for cosmetic reasons. The standard GP pathway for androgenetic alopecia ends with prescription medications such as finasteride or topical minoxidil, not surgical referral. Surgical options are considered only when hair loss results from a documented medical cause that meets strict clinical criteria.

The conditions that may qualify for reconstructive consideration include:

  • Severe burns causing permanent scalp damage
  • Traumatic scalp injuries with documented follicle destruction
  • Cicatricial alopecia, a scarring condition that destroys hair follicles permanently
  • Hair loss resulting from certain oncological treatments in specific clinical contexts

“Local Integrated Care Boards have discretionary power to fund reconstructive hair transplants but frequently decline such requests due to strict criteria and resource prioritisation. Even patients with legitimate medical grounds face an unpredictable and often lengthy funding process.”

The key word in every NHS exception is reconstructive , not cosmetic. A patient seeking to restore hair lost through male pattern baldness, even severe baldness, will not meet the threshold. ICB decisions are made case by case, and the outcome is rarely predictable. Private medical insurers apply the same reconstructive versus cosmetic distinction, and the bar is equally high.

How to evaluate your private insurance policy for hair restoration coverage

Reading a policy schedule carefully before making any assumptions is the most reliable way to avoid a denied claim. Policy exclusions are absolute denials of claims and do not affect your deductibles or active coverage for other conditions. They are permanent features of your contract, not temporary restrictions.

Follow these steps when reviewing your policy:

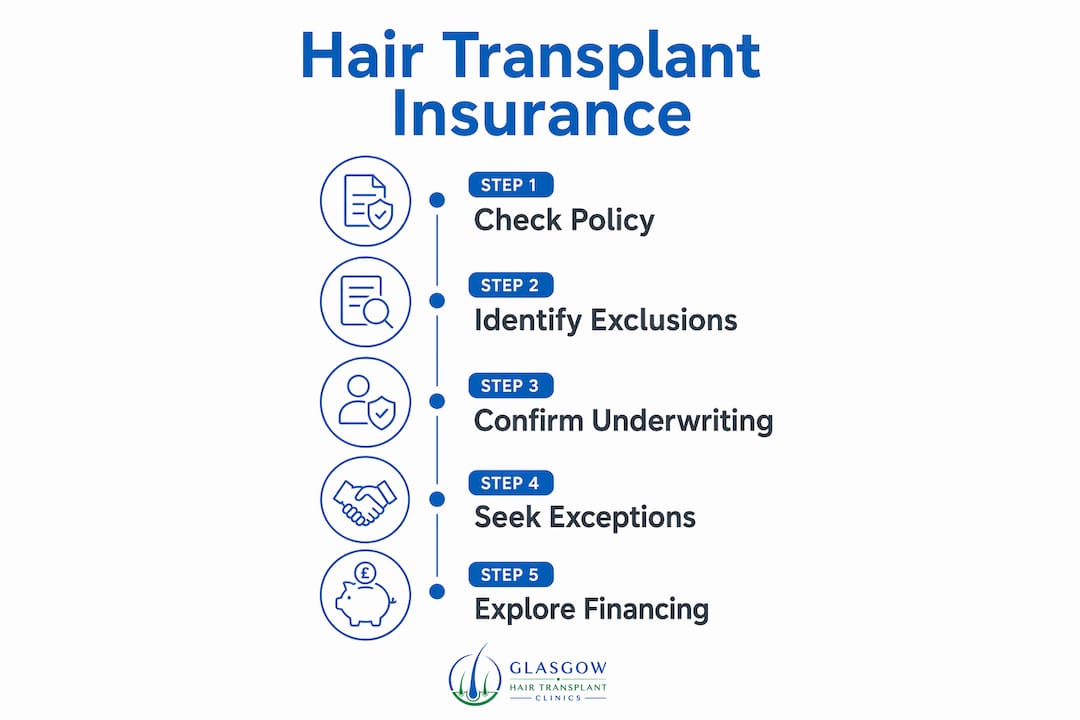
  1. Locate the exclusions schedule. This is usually a separate document within your policy pack, often titled “General Exclusions” or “What Is Not Covered.”
  2. Search for cosmetic surgery clauses. Any reference to aesthetic, elective, or appearance-related treatments will cover hair transplants by default.
  3. Check the pre-existing conditions section. Identify whether your policy uses moratorium underwriting or full medical underwriting, as this determines how hair loss history is treated.
  4. Review waiting periods. Some policies impose waiting periods for certain conditions. Hair loss treatments are typically excluded outright rather than subject to a waiting period.
  5. Contact your insurer in writing. Request written confirmation that hair transplant surgery is excluded. Keep this on file.

Full medical underwriting offers greater certainty because exclusions are agreed and documented at the point of application. Moratorium underwriting feels simpler at the outset but creates ambiguity that almost always resolves against the patient when a claim is submitted.

Pro Tip: If you are comparing policies, choose full medical underwriting. You will know exactly what is excluded before you pay a single premium, which makes financial planning far more reliable.

What are the real costs of a hair transplant in the UK?

The financial reality of self-funding a hair transplant in the UK is significant. A mid-sized procedure costs approximately £10,000 to £14,000 depending on graft count, technique, and clinic location. That figure does not include the full picture of associated costs.

You should budget for the following additional expenses:

  • Initial consultation fees (often £100–£200, though some clinics offer free consultations)
  • Pre-operative blood tests and scalp assessments
  • Post-operative medications including antibiotics and anti-inflammatory drugs
  • Follow-up appointments over a 12-month period
  • Time off work during the recovery phase, typically 7–14 days

Medical tourism has become a widely discussed alternative. Turkey-based clinics offer comparable procedures for £2,200 to £3,800, often with accommodation, airport transfers, and medication included in the package price. The cost saving is real and substantial.

Cost factor UK private clinic Turkey-based clinic
Procedure cost £10,000–£14,000 £2,200–£3,800
Accommodation Patient’s own cost Often included
Follow-up care Included or charged separately Variable
Regulatory oversight CQC, GMC registered Varies by provider
Travel cost Minimal £150–£400 return flight

The regulatory difference matters. UK clinics registered with the Care Quality Commission (CQC) and surgeons on the General Medical Council (GMC) register operate under enforceable standards. Overseas providers vary considerably. If you consider treatment abroad, verify the clinic’s accreditation independently before committing any payment.

What financial options exist for patients funding a hair transplant?

Insurance rarely covers hair transplant surgery, which means most patients fund the procedure entirely from personal savings or financing arrangements. The hair loss treatment options available in the UK range from non-surgical approaches costing a few hundred pounds to full FUE procedures at the higher end of the cost scale. Understanding the full spectrum helps you plan a realistic budget.

Practical financing routes include:

  • No-deposit payment schemes offered by specialist clinics, allowing you to begin treatment without a large upfront sum
  • Personal loans from high-street banks or specialist medical finance providers
  • Monthly instalment plans arranged directly with the clinic
  • Savings plans built over 12–18 months if the procedure is not urgent
  • Partial coverage in the rare reconstructive cases where a private insurer agrees to fund a portion of the procedure

Glasgowhairtransplantclinics offers a no-deposit scheme that allows patients to spread the cost of treatment without paying the full amount before their procedure date. This removes one of the most common barriers to accessing quality surgical care in the UK. Transparent pricing and a free consultation process mean you can understand your total cost before making any financial commitment.

Key takeaways

Insurance does not cover hair transplants in the UK because they are classified as cosmetic procedures, making personal financial planning the single most important step for anyone considering surgery.

Point Details
Insurance exclusion is universal All UK PMI policies exclude cosmetic surgery, including FUE and FUT hair transplants.
NHS exceptions are extremely rare Only reconstructive cases linked to burns, injury, or cicatricial alopecia may qualify for NHS funding.
Moratorium underwriting adds risk Pre-existing hair loss is automatically excluded under moratorium policies, with no room for appeal.
UK costs are substantial Mid-sized procedures cost £10,000–£14,000 in the UK; Turkey-based alternatives range from £2,200–£3,800.
Financing options exist No-deposit schemes and instalment plans make UK treatment accessible without full upfront payment.

The insurance reality most patients discover too late

Patients often arrive at a consultation having assumed their private health insurance would cover at least part of the cost. That assumption is almost always wrong, and discovering it late in the process causes unnecessary stress and delay.

What I have observed consistently is that the patients who plan best are those who treat the insurance question as settled from the outset. They accept that coverage is not coming, set a realistic budget early, and focus their energy on choosing the right clinic and technique rather than pursuing unlikely funding routes.

The reconstructive exceptions are real, but they apply to a very small number of people. If you experienced hair loss due to a burn, a traumatic scalp injury, or a confirmed diagnosis of cicatricial alopecia, it is worth raising the matter with your GP and requesting an ICB referral. For everyone else, the honest answer is that you will be self-funding, and the sooner you accept that, the better your planning will be.

One area where I see patients make avoidable mistakes is in comparing overseas and UK costs without accounting for the full picture. A £3,000 procedure in Turkey is not directly comparable to a £12,000 procedure in Glasgow if the overseas clinic lacks verifiable accreditation. The before and after results of a procedure tell you a great deal about a clinic’s standards. Always ask to see them before you decide.

— Harley

Glasgowhairtransplantclinics: transparent pricing and expert guidance

Glasgowhairtransplantclinics provides hair transplant procedures across Glasgow and the wider UK, with surgeons on the GMC register and clinics registered with the CQC and the Hair Industry Standards body. Every patient receives a free consultation, either online or face to face, with clear cost information provided before any commitment is made. The clinic’s no-deposit scheme means you can access FUE, DHI, and PRP treatments without needing the full procedure cost upfront. If you are weighing your financial options and want straightforward advice from a qualified team, request a consultation and get a personalised quote tailored to your hair loss pattern and goals.

FAQ

Does insurance cover hair transplants in the UK?

No. All UK private medical insurance policies exclude hair transplants as cosmetic procedures. The NHS funds surgery only in rare reconstructive cases linked to burns, scalp injury, or cicatricial alopecia.

What is the average cost of a hair transplant in the UK?

A mid-sized hair transplant in the UK costs approximately £10,000 to £14,000, with additional costs for consultations, medications, and follow-up appointments.

Can the NHS ever fund a hair transplant?

The NHS can fund hair transplants in very rare reconstructive cases, but Integrated Care Boards frequently decline such requests due to strict eligibility criteria and resource constraints.

What is moratorium underwriting and how does it affect hair transplant claims?

Moratorium underwriting automatically excludes any condition that existed within five years before the policy start date. Hair loss present before the policy began will result in an automatic claim denial without further investigation.

Are there financing options for hair transplants if insurance will not cover the cost?

Yes. Many UK clinics, including Glasgowhairtransplantclinics, offer no-deposit schemes and monthly instalment plans. Personal loans from medical finance providers are also a common route for patients funding the procedure independently.

Recommended

Hair transplant insurance in Denmark: checking your cover

Ask your insurer about the exact treatment and obtain a written decision before booking. Clinical suitability, private insurance and public reimbursement need separate checks.

Reviewing insurance documents and treatment costs
Published
12 July 2026
Updated
13 September 2026

Will insurance pay for a hair transplant in Denmark?

Coverage depends on the policy, the reason for treatment and any approval conditions. This page does not promise that a hair transplant will be covered, and it does not describe every Denmark policy as having the same exclusions. Ask your insurer to assess the specific proposed treatment before you pay a deposit.

Give the insurer the clinician’s diagnosis, procedure description, treatment location and written quote. Ask for a decision in writing, including any limits, excess, exclusions or conditions. Until cover is confirmed, plan on being responsible for the quoted cost.

Medical assessment and funding are separate decisions

Hair loss has different causes. A clinician may recommend investigation or treatment for scalp disease, while a separate decision is needed about whether transplantation is suitable. An insurer can also treat the consultation, diagnostic work, medicines and surgery as different items.

If hair loss follows injury, burns, illness or another medical event, discuss the appropriate clinical pathway with your doctor. The presence of a medical cause does not by itself establish insurance entitlement or public funding for a particular procedure.

How to check your policy

  • Read the policy schedule, general exclusions and any personal exclusions or endorsements.
  • Look for wording about hair loss, cosmetic or reconstructive treatment, pre-existing conditions and planned treatment abroad.
  • Ask whether the proposed consultation, tests, medicines, operation and follow-up are each covered.
  • Confirm whether a referral or prior authorization is required and whether the proposed clinician and location are accepted.
  • Ask about the maximum benefit, excess, co-payment and whether you must pay first and claim later.
  • Request the decision and any conditions in writing before booking.

Do not rely on a description of another insurer’s policy or a general article from another country. An employer health plan, private medical policy, travel policy and public healthcare entitlement are different arrangements.

What information may the insurer need?

Ask the insurer which documents it requires and how to send them securely. It may ask for the diagnosis, relevant history, referral, treatment plan, itemised quotation and proposed dates. Provide accurate information and keep copies of the decision and any claim correspondence.

The clinic can explain the proposed care and provide treatment information. It cannot guarantee an insurer’s decision or describe an appearance-related procedure as medically necessary simply to obtain cover.

Public healthcare and cross-border treatment

If you are seeking public funding or reimbursement, ask the relevant authority about your individual circumstances before arranging private surgery. A private booking is not evidence of entitlement to reimbursement.

The Danish Patient Safety Authority explains that reimbursement for treatment purchased in another EU/EEA country is conditional, and some care requires prior approval. Patients insured outside Denmark should contact the authority responsible for their cover. See its official guidance on treatment in the EU/EEA. These rules do not establish that a hair transplant is covered.

The European Health Insurance Card does not cover travel undertaken for planned treatment. Do not use possession of the card as confirmation that a private hair transplant will be paid for.

Travelling to Copenhagen for treatment

Patients from Sweden or Norway should ask their insurer about planned private treatment in Denmark and the arrangements for complications or further reviews after returning home. Check travel and accommodation cancellation terms separately.

Ask the treating clinic who you would contact for a concern, where an examination could take place and which further care could be charged. Insurance questions should be settled before travel where possible; they should never delay seeking help for an urgent medical problem.

If cover is declined

Ask the insurer to identify the policy wording and explain its decision. If you believe information was missing or the decision was incorrect, use its review or complaints process and check the stated deadlines. Do not assume an appeal will change the outcome.

You can then consider whether to wait, seek independent advice or fund care yourself. Discuss treatment timing and alternatives with the clinician. There is no need to commit to surgery while the clinical or financial position remains unclear.

Budgeting for a self-funded procedure

Denmark Hair Transplant Clinics provides individual written quotations in DKK. Check the proposed graft plan, procedure, aftercare and exclusions rather than using a copied overseas price table. Our cost information and booking terms explain what to request.

Allow for travel, accommodation if needed, time away from work and costs outside the quote. Any finance arrangement would need separate written terms; no particular lender, repayment plan or no-deposit offer is advertised here.

Frequently asked questions

Does a doctor’s recommendation guarantee cover?

No. Clinical suitability and policy eligibility are separate. Obtain the insurer’s written decision for the exact care proposed.

Can the clinic guarantee reimbursement?

No. The insurer or responsible public authority makes that decision. The clinic can provide information about the treatment and its price.

What should I bring to a consultation?

Bring your medical and treatment history, current medication list and any insurer requirements you have received. Arrange the clinical assessment before deciding on a procedure or borrowing to fund it.
Clarify your treatment plan

Our Denmark team can explain the proposed assessment and written quotation. Your insurer or public authority must confirm any funding.

Request a consultation
Man checking his receding hairline in a mirror
By Dr Harpreet Kalra September 14, 2026
Understand hair loss studies and treatment statistics with source populations, study dates and practical context for readers in Denmark.
A grey scoop filled with white creatine monohydrate powder
By Dr Harpreet Kalra September 7, 2026
Does creatine cause hair loss? Read what the 2009 study and 2025 trial found, their limits, and what to do if your hair is thinning.
Hair transplant graft-zone diagram showing estimated graft counts for the hairline, mid-scalp and crown areas.
By Dr Harpreet Kalra September 4, 2026
Typical graft ranges for the hairline, crown and advanced loss, with donor density, coverage and long-term planning explained clearly.
Show More